News
Addressing Longevity Risk: Planning for a Retirement That Lasts
When you picture your retirement, what do you see? Perhaps it’s a cross-country road trip, dedicating time to a long-neglected hobby, or finally spending uninterrupted weeks with family. For decades, the financial focus leading up to these years has primarily been on accumulation. One of the biggest concerns for retirees today is running out of money, so we often focus on how much we can and should save for retirement.
However, as life expectancies lengthen, it is time to look beyond just a dollar amount and asset accumulation. When you retire, you move from a phase of accumulation to one of distribution, and the central question becomes: How long can my money last? Planning your retirement with that question in mind can help manage what’s known as longevity risk: living longer than expected and depleting your savings. With many retirees living well into their 90s, preparing for a longer time horizon is an important consideration in your retirement strategy.
The Gift of Longevity
Living longer is a remarkable gift, giving you more time to explore passions and enjoy life. Yet, a longer timeline can also act as a multiplier for standard retirement variables like market fluctuations, inflation, and healthcare costs. If a retirement strategy is built on the assumption that it only needs to span 20 years, stretching it to 30 or more years introduces a completely different mathematical reality.
Priming Your Portfolio for Three or More Decades
Creating a durable retirement plan involves looking ahead and factoring in the elements that will accompany a longer life. Here are key areas to address when designing a strategy with staying power:
1. Planning for Inflation
Over the course of three decades, the cost of living will naturally rise. Inflation quietly diminishes purchasing power over time, meaning the income that covers your expenses at age 65 will need to be proportionately higher to cover those same expenses at age 85. A forward-thinking portfolio incorporates mechanisms to counter inflation. You might consider a strategy that maintains a portion of assets in investments intended to keep pace with the rising cost of goods and services.
2. Funding Travel and Hobbies
Many retirement plans focus heavily on the first decade, which can often be the most active years. During this time, travel and hobbies can be front and center. One potential strategy is to separate core living expenses from discretionary income. By exploring options designed to create a potential income stream to cover foundational needs like housing and groceries, your investment portfolio can be positioned to support your lifestyle goals.
3. Navigating Rising Healthcare Costs Associated with Aging
As we age, healthcare expenses naturally increase, and the potential need for long-term care becomes a realistic consideration. Instead of letting these future costs become a source of worry, a proactive plan simply anticipates them. Incorporating tools like Health Savings Accounts (HSAs), exploring long-term care options, and actively planning for Medicare premiums can help integrate these costs into your overall strategy.
4. Creating a Tax-Efficient Withdrawal Strategy
A long retirement means addressing Required Minimum Distributions (RMDs) and potential tax shifts later in life. Relying strictly on a fixed withdrawal percentage, like the traditional 4% rule, might not fit a 35-year horizon perfectly. Prioritizing tax efficiency in how and when you withdraw funds can help manage your principal balance for the long haul.
Embracing the Long View
Addressing longevity doesn’t need to be intimidating. It is just another piece of a well-balanced retirement strategy and can be managed with proactive, deliberate planning. Rather than viewing your retirement as a rigid timeline, think of it as a dynamic, evolving journey. Meeting regularly with your advisor allows you to review your strategy, adapt to changing markets, and make thoughtful adjustments along the way.
The goal is to approach your retirement with excitement and clarity, knowing your plan is structured with your full lifespan in mind. By acknowledging the realities of longevity, we can construct a strategy aimed at supporting you through all the chapters of your retirement. Get in touch with us today to get started.
Sources:
https://www.kiplinger.com/retirement/how-to-age-proof-your-retirement-plan
https://www.kiplinger.com/retirement/retirement-planning/longevity-the-retirement-risk-no-one-likes-to-talk-about
This information is provided as general information and is not intended to be specific financial guidance. Before you make any decisions regarding your personal financial situation, you should consult a financial or tax professional to discuss your individual circumstances and objectives. Guarantees are backed by the financial strength and claims-paying ability of the issuing insurance company. his material is designed to provide general information on the subjects covered. Pursuant to IRS Circular 230, it is not intended to provide specific legal or tax advice and cannot be used to avoid penalties or to promote, market, or recommend any tax plan or arrangement. You are encouraged to consult your personal tax advisor or attorney. The source(s) used to prepare this material is/are believed to be true, accurate and reliable, but is/are not guaranteed. Please note you are leaving the website. We have no control over third-party sites and do not guarantee the information, products, or services received.
SWG 5790325-0726
College Tuition or Retirement Confidence? How About Both?
You’ve worked hard to build a stable life for your family, and as your child nears high school graduation, it’s natural to want to extend that stability by helping them pursue higher education. Yet beneath the pride and excitement, a quiet anxiety can sometimes surface: how will the cost of tuition impact your own financial independence? Many parents find themselves wondering if it’s possible to pay for college while keeping their retirement on track.
A Unified Strategy for College and Retirement
The good news is that it is possible to do both! You don’t have to fall into the trap of believing you must sacrifice your own future for your child’s. With proactive planning, smart funding strategies, and strategic asset coordination, you can balance both milestones while remaining focused on your long-term objectives. Let’s take a look at some considerations to help you tackle both goals.
1. Understanding Net Price vs. Sticker Price
One of the first things to note is that the published price of a school is not necessarily the price you’ll have to pay. Many parents mistakenly assume that state schools are the only budget-friendly option and rule out elite private colleges based entirely on advertised costs. However, in 2024-25, roughly $275 billion in grant aid was awarded to undergraduate and graduate students, with higher education institutions themselves serving as the largest providers of grant funding and average tuition discount rates at private colleges of over 50%. It’s important to keep your options open when considering which schools to apply to and which may be the best fit for your child. When you understand how admissions and financial aid formulas intersect, your actual out-of-pocket cost could end up substantially lower than the list price.
2. Always Apply for Financial Aid and Scholarships
A common misconception among high-earning parents is that their income disqualifies them from receiving financial aid. This mistake can lead some to skip the aid process entirely and pull funds straight from their retirement accounts. This is a scenario that may be worth avoiding, depending on your individual circumstances. Between potential penalties for early withdrawal, possible tax implications, and reduced opportunity for future investment growth, the cost of using your retirement account to fund education expenses may be significant. Instead, it’s important to complete the FAFSA and CSS forms to see what you might be offered. You may be surprised. High earners can sometimes qualify for tuition discounts through merit aid at the right schools. Regardless of your income level, many families can still qualify for some form of aid or institutional discount.
3. Strategic Asset Positioning
One strategy that may help preserve your retirement assets lies in how you position your wealth years before your child applies to college. The FAFSA and the CSS Profile develop a Student Aid Index (SAI) to determine your need, but they use completely different criteria for their evaluations. For example, the FAFSA excludes certain assets from its formula altogether, including your primary home equity, retirement accounts (like 401(k)s and IRAs), and life insurance policies.
If you hold significant assets in reportable accounts, it may increase your SAI and reduce your aid eligibility. By strategically moving reportable assets into non-reportable vehicles, like cash-value life insurance or non-qualified annuities, you may be able to position your assets in a way that aligns favorably with financial aid calculations. This advanced coordination may serve a dual purpose:
- It may help improve your child’s eligibility for financial aid.
- It can place your assets in financial vehicles that can offer tax-deferred growth potential, reduced market volatility, and a preserved income stream for your retirement.
Seek Professional Guidance
Even with a generous financial aid package, a gap can still remain between the total cost of attendance and the aid received. When deciding how to bridge this remaining balance, remember that every family has two main funding buckets to draw from: assets and borrowing. Rather than liquidating retirement assets, like your 401(k), which may affect your long-term retirement strategy, consider exploring alternative funding approaches that may help cover education expenses. Working with a financial professional can help you evaluate these options and determine an approach that aligns with your financial goals.
You don’t have to choose between your child’s degree and your retirement dreams. Reach out to us today to create a comprehensive, unified strategy that helps support your future while helping fund theirs.
Sources:
https://research.collegeboard.org/trends/student-aid/highlights
https://research.collegeboard.org/media/pdf/Trends-in-College-Pricing-and-Student-Aid-2025-final_1.pdf
https://studentaid.gov/help-center/answers/article/how-sai-calculated
https://www.collegemoneymethod.com/how-fafsa-versus-css-profile-count-parent-assets/
https://www.collegedata.com/resources/pay-your-way/how-student-and-parent-assets-affect-your-financial-aid
This information is provided as general information and is not intended to be specific financial guidance. Before you make any decisions regarding your personal financial situation, you should consult a financial or tax professional to discuss your individual circumstances and objectives.
This blog is designed to provide general information on the subjects covered. Pursuant to IRS Circular 230, it is not intended to provide specific legal or tax advice and cannot be used to avoid penalties or to promote, market, or recommend any tax plan or arrangement. You are encouraged to consult your personal tax advisor or attorney.
The source(s) used to prepare this material is/are believed to be true, accurate and reliable, but is/are not guaranteed.
SWG 5782311-0726
Pros and Cons of Keeping Your Assets in Your Retirement Accounts
As you get closer to retirement, you may start to wonder what you should be doing with the assets you’ve saved up. You’ve probably accumulated a significant sum for retirement, but how do you put that sum to work so you can maintain your lifestyle throughout your retirement? Do you leave your funds where they are, or are there other options you should consider?
There is no one-size-fits-all answer. Managing this transition requires balancing regular income needs, access to cash if you need it, market volatility, and overall risk/reward tradeoffs. Let’s take a look at the pros and cons of your two primary paths.
Path A: Leaving Assets in Your Retirement Accounts
For many pre-retirees, keeping their nest egg entirely within traditional retirement accounts is the default choice.
The Pros:
- Tax-Deferred Growth: Your assets can continue to compound without having to pay annual taxes on your accumulated funds until you start making withdrawals.
- Inflation Protection: By keeping a healthy amount of equity in market-based funds, your portfolio may be able to outpace inflation over a multi-decade retirement.
- Simplicity: Your accounts are already established, making them easy to track and monitor.
The Cons:
- Market Volatility Exposure: Leaving your assets in the market means you remain exposed to downturns. If the market dips just as you retire, drawing income from a shrinking balance could alter your portfolio’s longevity.
- The Risk/Reward Dilemma: Traditional accounts don’t inherently generate monthly paychecks. You must manage the trade-off between growing your money and spending it.
- Potential Tax Surprises: If the government changes tax brackets in the future, or if you haven’t made a plan that includes Required Minimum Distributions (RMDs) from your traditional 401(k), you may be pushed into a higher tax bracket, which could affect your taxes on Social Security or Medicare premiums.
Path B: Exploring Other Options to Fill Specific Needs
Instead of leaving everything in one place, you might consider alternative tools that help address specific needs or concerns.
The Pros:
- Customized Cash Flow: Instead of trying to manage your own withdrawals, you could consider annuities or life insurance products for income or access to cash. For example, Fixed Indexed Annuities (FIAs) can function a bit like a personal pension and can be customized with riders for lifetime payments, while some types of life insurance policies may provide the benefits of life insurance while allowing you to access their cash value if you need it.
- Volatility Insulation: Modern annuity and insurance products can also be used for principal protection, allowing you to benefit from interest accumulation while providing a premium protection feature so you don’t lose your original investment if the market crashes.
- Inflation Pacing: Standard taxable brokerage accounts can help give you the flexibility to invest in dividend-paying stocks or growth equities, allowing your assets to continue to grow, and you may be able to add inflation riders to certain annuity products. Both of these options can help your funds to keep up with inflation.
The Cons:
- Complexity: Managing multiple financial vehicles requires more strategic oversight and planning. It’s important to talk with a financial advisor about how to utilize these products in the most effective way for your financial goals and concerns.
- Liquidity Tradeoffs: Some options, like annuities, may mean you don’t have immediate, total access to your funds.
So, What’s Next?
Transitioning into retirement isn’t an all-or-nothing decision. It is about shifting your focus from seeking to increase your total savings to using those savings to maintain your lifestyle throughout retirement. Whether you leave your assets where they are or branch into other vehicles, speaking with a financial professional about your goals and the retirement risks that concern you most is the best way to help ensure you have a well-positioned plan tailored to you and your retirement lifestyle.
Sources:
https://www.investopedia.com/terms/d/definedcontributionplan.asp
https://www.investopedia.com/terms/a/annuity.asp
This material is intended for educational purposes only and is not intended to serve as the basis for any purchasing decision. The source(s) used to prepare this material is/are believed to be true, accurate and reliable, but is/are not guaranteed.The interest credited is limited by either placing a cap on the amount of interest that can be earned (“cap” rate) and/or requiring a specified rate that must be surpassed within the index before interest will be credited (“spread rate”). The interest credited on your contract may be affected by the performance of an external index. However, your contract does not directly participate in the index or any equity or fixed interest investments. You are not buying shares in an index. Guarantees are backed by the financial strength and claims-paying ability of the issuing insurance company. An annuity is intended to be a long-term, tax-deferred retirement vehicle. Earnings are taxable as ordinary income when distributed, and if withdrawn before age 59½, may be subject to a 10% federal tax penalty. If the annuity will fund an IRA or other tax qualified plan, the tax deferral feature offers no additional value. Qualified distributions from a Roth IRA are generally excluded from gross income, but taxes and penalties may apply to non-qualified distributions. Consult a tax advisor for specific information.
SWG 5643879-0626
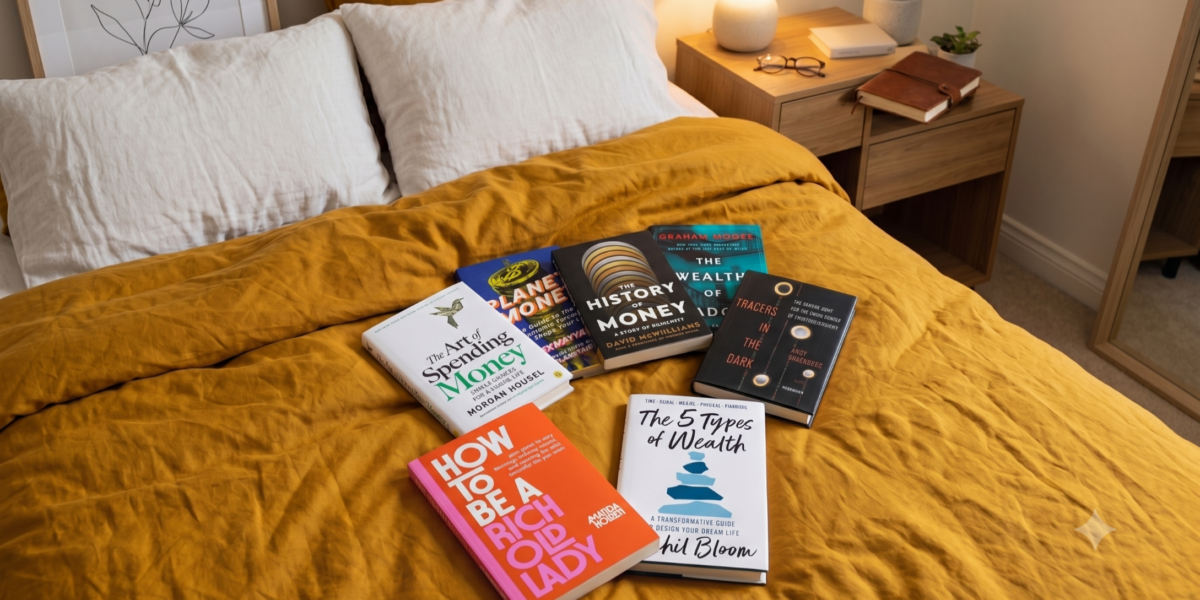
7 Books About Money to Enlighten and Entertain
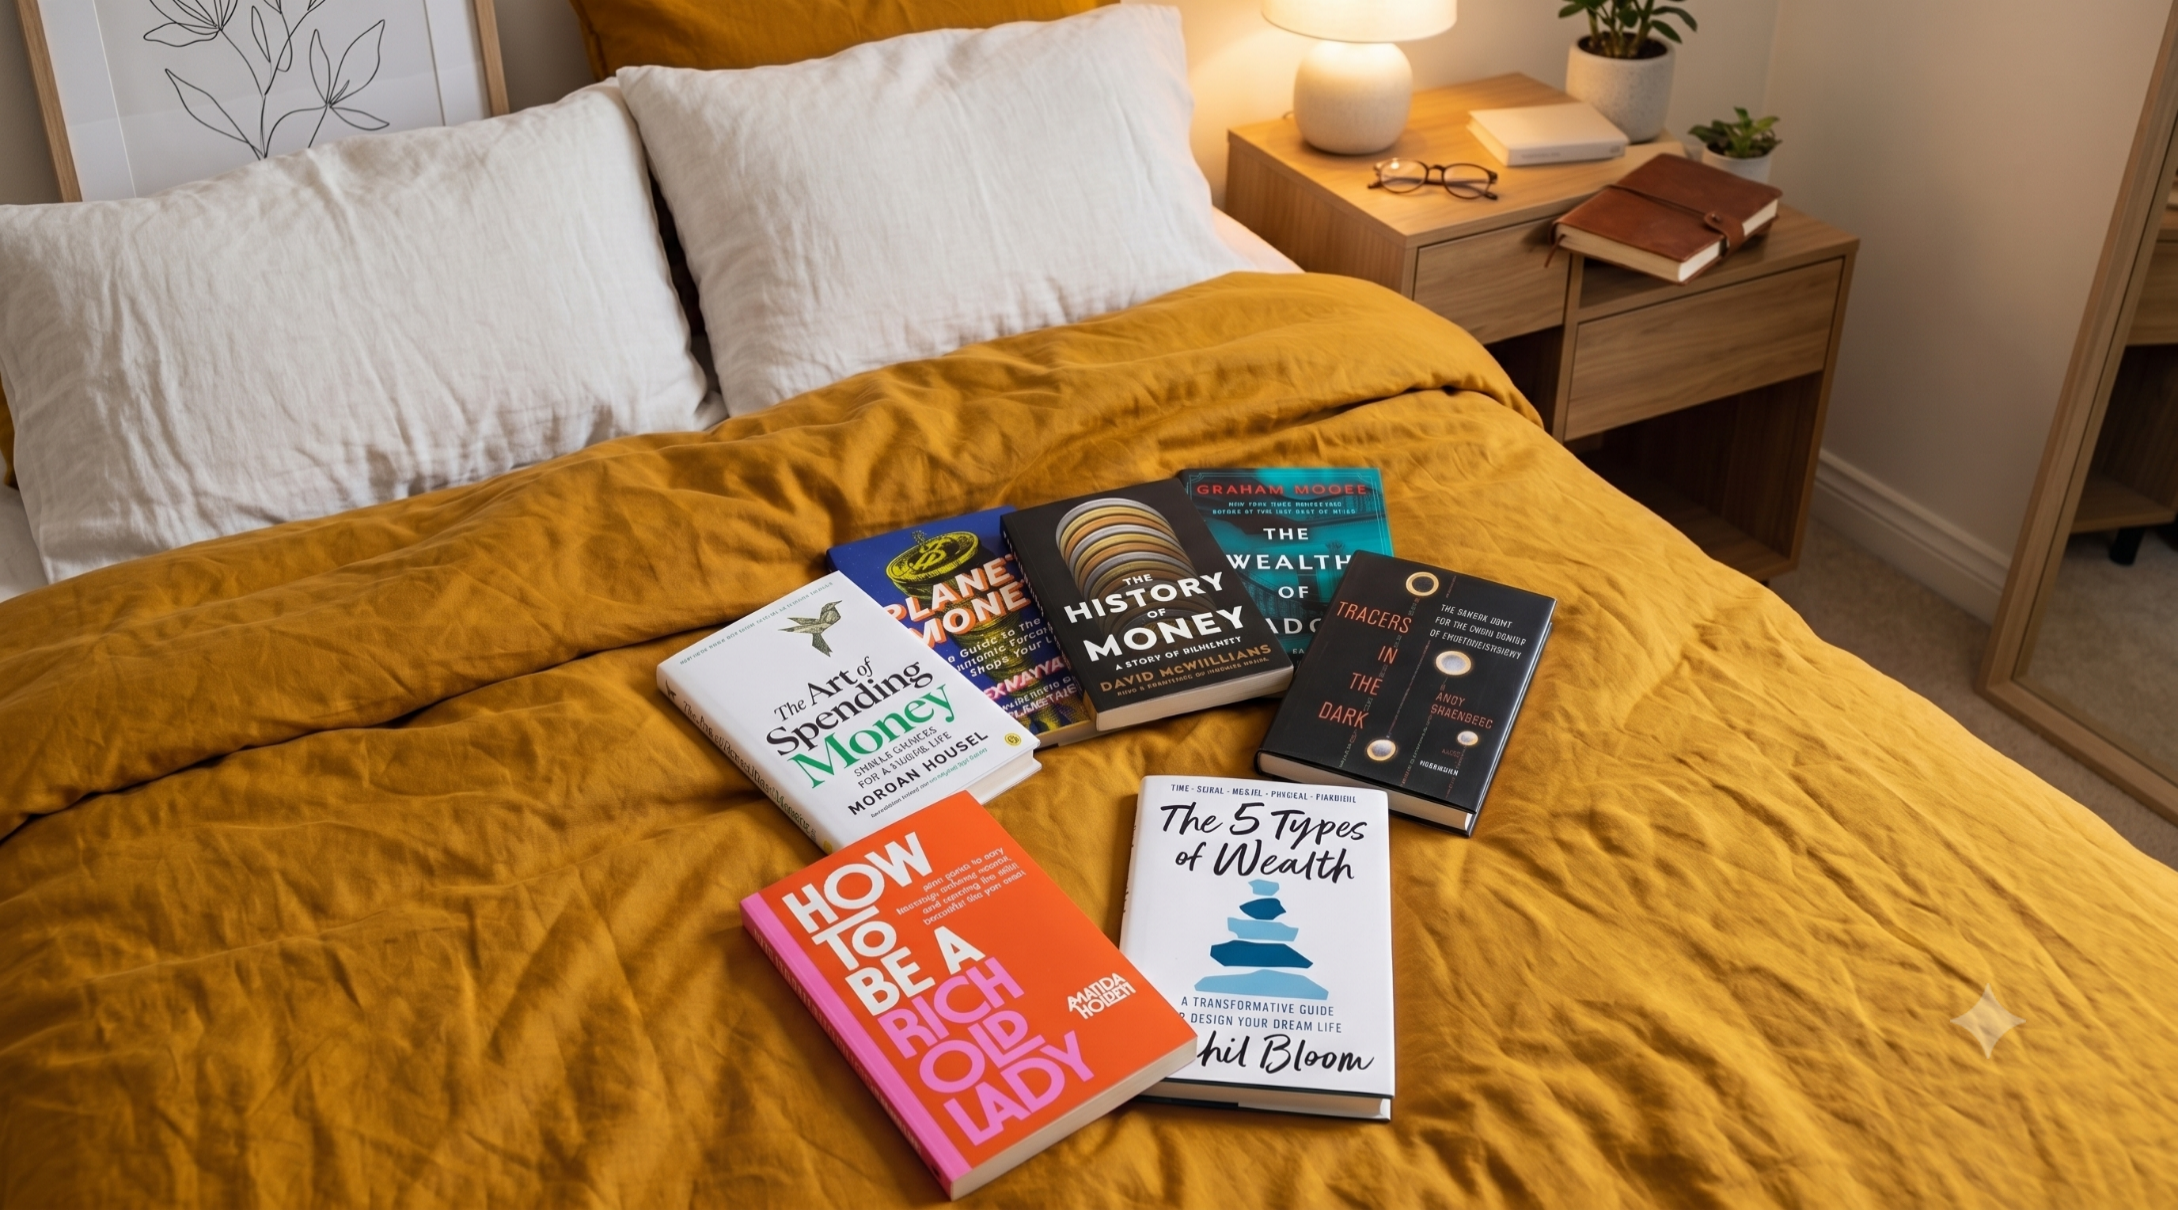
Toss aside those crusty old finance books (though some are tried and true and worth the read!). Let’s check out some newer books to add to your TBR list!
Planet Money: A Guide to the Economic Forces That Shape Your Life
by Alex Mayyasi & the Hosts of NPR’s Planet Money
“Readers, from the economically curious to the Financial Times devotee, will find these stories illuminating and engaging.”― Booklist (starred review)
The world’s most popular economics podcast is now a book! Millions of listeners have tuned in to uncover the hidden forces shaping our world. Now, whether you’re a loyal subscriber or discovering it for the first time, this book offers something fresh for everyone. Inside, you’ll explore how economics impacts every corner of our lives, from career and success to love, family, and leisure. Among the stories, you’ll discover how the “worst contract in sports history” is actually a blueprint for retirement, how the second-smallest U.S. state became the referee of global business, and the practical lessons you can apply to your own life.
The History of Money: A Story of Humanity
by David McWilliams
“Learned, lively and often irreverent, David McWilliams’s The History of Money is rich with surprising details about currency, then and now.” ―The New York Times
From clay tablets to cryptocurrency, economist David McWilliams takes us on a journey through humanity’s history using the lens of its most significant tool. McWilliams connects money to important historical events in ways you might not expect, with sections on the ancient world, medieval, revolutionary, and modern ages. He travels the globe in his adventurous and educational narrative, introducing readers to a cast of characters and events that ultimately changed our world. If you love history, you’ll want to check this one out.
The Art of Spending Money: Simple Choices for a Richer Life
by Morgan Housel
“If you’re looking to understand how to use your money to make you truly happy, here it is. You’ll never shop the same way again.” —Jean Chatzky, bestselling author of How to Money and Women with Money
The bestselling author of The Psychology of Money moves from advice on investing and saving your money to spending it. This book explores the age-old question of whether money can buy happiness while encouraging readers to shift their mindset and make the most of what they have right now. Housel looks at how past experiences, social pressures, and psychology affect our behavior with money, and how we can dissect these factors to make more meaningful choices about our spending and lead happier, more fulfilling financial lives.
How to Be a Rich Old Lady: Your Guide to Easy Investing, Building Wealth, and Creating the Wild, Beautiful Life You Want
by Amanda Holden
“A sharp and funny guide for women on investing and building wealth . . . Readers will feel equipped and inspired to live their best lives.” —Publishers Weekly
If you’ve ever wanted someone to take you by the hand and walk you through the world of finance or needed a friend to text you the ins and outs of investing… This is the book for you. Amanda Holden spent years working in investment management before launching her own financial education company, and she’s brought her lessons to the masses in this clever, humorous, and down-to-earth book. She provides hands-on tools and worksheets to help guide you on your path to financial independence, so you can have the knowledge and an action plan to become your own version of “a rich, old lady.”
The Wealth of Shadows
by Graham Moore
“Based on astonishing true events, The Wealth of Shadows is both a gripping, cinematic story of wartime subterfuge, and a powerful reminder of how even the most unlikely people can become resistance fighters during times of crisis.”—Flynn Berry, New York Times bestselling author of Northern Spy and Trust Her
Bestselling novelist and Academy Award-winning screenwriter Graham Moore takes us back to 1939 in this historical thriller based on a true story. Tax attorney Ansel Luxford moves himself and his young family to Washington, D.C., to join a covert group within the Treasury Department. Their task? Taking down Nazi Germany through economic warfare. An ordinary man now thrust into a world of espionage, danger, and deception, Ansel must outsmart some of the greatest financial leaders of his day and become a hero using the only weapon he knows how to wield: money.
The 5 Types of Wealth: A Transformative Guide to Design Your Dream Life
by Sahil Bloom
“A powerful call to action to think deeply about what lights you up—and a guide for how to build a life of meaning and purpose.”—Tim Cook, CEO of Apple
This New York Times and USA Today bestseller reminds us that wealth is not just financial. Sahil Bloom encourages readers to explore all 5 types of wealth: Time, Social, Mental, Physical, and Financial, in order to transform their lives. Through storytelling, science, history, and wisdom, this book is an appeal to readers to think about what truly matters in their lives and readjust accordingly.
Tracers in the Dark: The Global Hunt for the Crime Lords of Cryptocurrency
by Andy Greenberg
“Immensely readable… Greenberg is known for his ability to explain complicated technology in a way anyone can understand, and he doesn’t disappoint when he tackles crypto…. The whole smoky world of crypto starts to open up… [He] takes readers on a romp through some of the most infamous dark web takedowns in recent memory.” —Washington Post
Andy Greenberg is an award-winning cybersecurity reporter who takes us into the deep, seedy underbelly of digital black markets and the way cryptocurrency contributes to illegal activity online. With no banks, ledgers, or government oversight, cryptocurrency enables criminals to engage in illicit activity without leaving a paper trail. This book uncovers the dogged characters and professionals who figured out how to crack Bitcoin’s anonymity, find the digital trail, and track down the bad guys.
This information is provided as general information and is not intended to be specific financial guidance. Before you make any decisions regarding your personal financial situation, you should consult a financial or tax professional to discuss your individual circumstances and objectives. Investment advisory and financial planning services are offered through Simplicity Wealth, LLC, an SEC-registered investment adviser. SEC registration does not constitute an endorsement of the firm nor does it indicate that the adviser has attained a particular level of skill or ability. Investing involves the risk of loss.
SWG 5584503-0626
Managing Market Volatility: How Gen X and Baby Boomers Navigate Shifting Financial Landscapes

Market volatility is a natural part of the financial ecosystem, but its impact varies depending on your specific stage of life. For members of Gen X who are currently in their peak earning years and steadily approaching retirement, sudden market swings can create noticeable anxiety. Meanwhile, Baby Boomers, many of whom have already transitioned into retirement, might view market fluctuations through the primary lens of wealth preservation. Comparing how these two distinct groups might respond to shifting markets helps highlight the different investment management strategies available for pre-retirees and retirees.
Gen X: Navigating Pre-Retirement Pressures
Gen X stands at an important financial crossroads. Often described as the sandwich generation, many Gen X individuals find themselves balancing the expenses of raising children and caring for aging parents at the same time. These financial pressures mean that a considerable number of Gen Xers feel like they’re behind schedule in reaching their future financial goals. Furthermore, most Gen Xers recognize that funding retirement is increasingly their own personal responsibility due to fewer traditional pension choices. For these pre-retirees, sudden market volatility introduces a difficult dilemma.
If you’re a Gen X investor, you might react to market swings by maintaining an overly conservative portfolio. You may hold a large amount of cash or short-term vehicles like CDs out of fear of market drops. While this strategy aims to avoid short-term losses, it can prevent the portfolio from growing enough to outpace inflation, which carries the long-term risk of falling short of your retirement goals. On the other hand, a more balanced approach involves a risk-adjusted portfolio, which blends growth-oriented assets with more stable options, allowing you to participate in market gains while helping to limit the impact of sudden downturns, though risk of loss can’t be entirely eliminated. But not all balanced approaches are the same, and some may address your needs more directly than others. There’s no harm in exploring many types of options and tools that are aimed at providing protection and/or growth potential, but it’s not easy to accurately evaluate your options without professional financial experience. That’s why a financial professional can be a valuable guide in constructing a plan that truly works for you.
Baby Boomers: Prioritizing Stability and Asset Preservation
If you’re a Baby Boomer, you’re navigating a later stage of the financial lifecycle. According to recent research from Equifax, Baby Boomers generally hold high levels of financial stability and have reduced their overall share of consumer debt significantly over recent years.2 Research also indicates that this generation prioritizes capital preservation and managing ongoing health expenses. Since Baby Boomers hold a substantial portion of national wealth, market volatility still presents unique risks for retirees who want to protect what they have built.
If you’re a Baby Boomer with a stock index-heavy 401(k), for example, a sudden market downturn can have a significant impact on your portfolio. If you hold too many equities and need to withdraw funds for daily expenses during a market decline, you may be forced to lock in losses, which can reduce the longevity of your retirement savings. To help mitigate this risk (called sequence of returns risk), Baby Boomers might focus on protection-oriented assets. Incorporating fixed-income strategies into your plans can help you protect your lifestyle, build a more predictable cash flow for your family’s everyday expenses, and, in some cases, maintain access to market upside potential (which may be capped or limited depending on the strategy used). But just like balanced strategies for Gen Xers approaching retirement, balanced strategies for Baby Boomers already in retirement aren’t all the same and could benefit from professional financial guidance.
Balancing Accumulation and Distribution
The distinction between these two generations underscores the core difference between accumulation and distribution strategies. Gen Xers in pre-retirement often need to focus on growing their accumulated assets while carefully managing risk, whereas retirees typically focus on generating stable income and avoiding large market losses. As Baby Boomers prepare to pass down significant assets in the upcoming wealth transfer, maintaining portfolio stability remains a primary goal.
Aligning Your Strategy with Your Life Stage
Navigating these choices efficiently requires careful planning. Gen Xers might look at their time horizon and evaluate if their risk tolerance aligns with their long-term objectives, and Baby Boomers might review their current asset mix to determine if they can cover their costs no matter the market. Every financial journey is unique, and adapting your strategy to your own specific life stage can help support your long-term financial stability. That’s why it can make a big difference to sit down with us so we can learn about your individual situation and help provide strategies that match your retirement goals.
Sources:
[1] https://www.morningstar.com/portfolios/how-handle-market-volatility-every-life-stage
[2] https://www.equifax.com/business/blog/-/insight/article/legacy-and-stability-why-baby-boomers-and-traditionalists-remain-the-gold-standard-for-financial-security/
This material is for educational and informational purposes only and is intended to provide a general overview of market behavior and generational financial perspectives. It should not be construed as individualized investment, insurance, legal, or tax advice. Market volatility strategies discussed are general in nature and may not be suitable for all investors. All investing involves risk, including the potential loss of principal. Past performance is no guarantee of future results. Sources are believed to be reliable and accurate; however, Simplicity Group and its affiliates do not independently verify or guarantee the completeness, accuracy, or timeliness of this information. Guarantees provided by insurance products, including fixed or fixed indexed annuities, are backed solely by the financial strength and claims-paying ability of the issuing insurance carrier. They are not bank deposits, are not FDIC insured, and are not obligations of any financial institution. SWG5664643-0626
Inflation’s Impact on Your Retirement

Planning for retirement requires many considerations, but perhaps none is as subtle or pervasive as the influence of inflation. While market volatility often captures the headlines, the gradual rise in the cost of goods and services acts as a constant force that can erode the purchasing power of the assets you worked for over time. Understanding this dynamic is a starting point for developing a long-term financial strategy.
The Subtle Erosion of Purchasing Power
Inflation represents the general increase in the cost of goods and services. When this happens, each dollar you hold buys a little less than it did previously. In the short term, this effect may seem minor, but as you plan for a retirement that could span multiple decades, even modest inflation rates can have a notable impact on your cost of living.
Think about the expenses you face today, such as healthcare, housing, and food. As these costs rise, the amount of money needed to maintain your preferred lifestyle also increases. If your savings do not grow at a rate that keeps pace with these rising costs, the real value of your assets declines. This is why financial planning often emphasizes real returns, which means the rate of return on an investment after accounting for the effects of inflation.
Impacts on Conservative Options and Fixed Income
As you approach retirement, you might naturally gravitate toward conservative investment options to limit exposure to market fluctuations. While these vehicles play a role in a balanced portfolio, they can be particularly vulnerable to inflationary pressures.
Fixed-income investments, such as traditional bonds, typically provide a set interest payment. When inflation rises, the real value of those fixed payments decreases. And if inflation leads to higher interest rates, the market value of existing bonds with lower interest rates often declines. So if you’re relying on these investments for regular income, this creates a situation where the income stream may lose its ability to cover rising expenses.
Savings Reserves and Cash
Maintaining a healthy savings reserve is important for liquidity and near-term needs. But holding excessive amounts of cash or keeping savings in accounts with very low returns can expose those funds to the effects of inflation. Because the interest earned on basic savings accounts is often lower than the rate of inflation, money kept in these accounts may lose purchasing power every year. Balancing the need for readily available cash with the necessity of growth is a challenge that often requires a measured approach to asset allocation.
Considering Strategies
Inflation’s impact on purchasing power is greater over longer periods of time, so you might think about different retirement strategies to help address it. Rather than relying on a single method, a common approach involves diversifying across different asset classes.
Some assets, such as equities or real estate, have historically shown the potential to outpace inflation over the long term. These investments carry their own risks, but they are often included in retirement portfolios to help maintain the real value of capital. Other options, such as Treasury Inflation-Protected Securities (TIPS) Bonds, are specifically designed to adjust their value or payouts based on inflation metrics.
Additionally, periodic reviews of your financial plan can be helpful. As your time horizon and goals evolve, adjusting your savings goals or withdrawal strategies may help you remain aligned with your objectives.
Navigating the influence of rising prices is a standard part of long-term financial management. By acknowledging the effects of inflation and considering a range of strategies, you can work toward a more prepared approach to your retirement years. Speaking with a financial professional can help you evaluate which methods might fit your specific goals and risk tolerance.
Sources:
https://thetradinganalyst.com/inflation-adjusted-return/
https://www.thrivent.com/insights/retirement-planning/how-does-inflation-affect-retirement-savings
This material is for educational purposes only and should not be construed as specific investment, legal, or tax advice. Investing involves risk, including the potential loss of principal. Asset allocation and diversification do not guarantee a profit or protect against loss in declining markets. Past performance is not a guarantee of future results. 5594718-0626
Celebrating National Investors Month: Long-Term Retirement Investing Basics for Pre-Retirees

August marks National Investors Month, with August 14, 2026, being National Financial Awareness Day. This is an important time to review financial habits and look closely at long-term retirement plans. If you’re one of the millions of Americans approaching retirement within the next few years, this month offers an opportunity to focus on foundational investing concepts, such as diversification and risk management. Transitioning from a full-time career to retirement involves careful planning, and understanding how to manage accumulated assets over this important period of your life can help you work toward your financial goals.
Balancing Saving and Investing in the Transition to Retirement
As individuals approach retirement, transitioning from accumulating wealth to preparing for income generation often involves thoughtful planning. An important element of this transition is understanding the distinction between saving and investing. Saving generally involves placing money in stable, liquid accounts, such as traditional bank savings accounts or certificates of deposit. This approach is helpful for pre-retirees who want to manage short-term expenses or establish an emergency fund, as the principal amount remains accessible. However, relying solely on savings may make it difficult to protect purchasing power against inflation over a retirement that could span multiple decades.
Investing involves allocating capital into assets like stocks, bonds, or mutual funds with the goal of generating a return over time. While market investments carry risk, they also offer the potential for greater growth than risk-averse vehicles. For pre-retirees, maintaining a suitable investment strategy helps support future lifestyle needs and allows accumulated wealth to potentially outpace the rising cost of goods and services. Striking a balance between accessible short-term savings and long-term investments is an important step when navigating the transition to retirement.
Navigating Risk Tolerance in the Transition to Retirement
As retirement nears, an individual’s risk tolerance often changes. In the earlier stages of a career, investors frequently focus on aggressive growth because they have many years to recover from market downturns. For pre-retirees, balancing growth with capital preservation becomes a more important consideration. Significant market volatility can be difficult to manage when an individual plans to begin withdrawing funds from their portfolio in the near future.
Evaluating personal risk tolerance involves assessing both the financial ability to withstand market losses and one’s sense of emotional comfort with market fluctuations. Pre-retirees may find it beneficial to consider shifting toward a more conservative asset allocation. This shift can help mitigate significant portfolio declines while still allowing for some investment growth during retirement years. Diversification across asset classes is another potential method to help manage risk as priorities shift from accumulation to distribution.
The Broad Goal of Target Date Funds
Many retirement accounts incorporate diversified investment options designed to simplify asset management over time. Target date funds represent one common strategy that pre-retirees often utilize within retirement accounts. The primary goal of these funds is to provide a structured investment path based on a specific anticipated retirement year.
As the target date approaches, the fund automatically adjusts its asset mix from a growth-oriented allocation to a more conservative allocation. This structure aims to reduce investment risk gradually over the long term without requiring the investor to manually rebalance their portfolio. It provides a convenient way for individuals to align their current investments with their expected retirement timeline, with the intent of supporting a smoother transition into the retirement years.
Embracing a Strategic Approach
National Investors Month in August 2026 serves as a reminder that long-term investing requires regular evaluation. Pre-retirees can use this period to review their current portfolios, analyze their risk tolerance, and explore suitable investment strategies. Working with a qualified financial professional can assist individuals in identifying options aligned with their unique needs. Taking these steps can help pre-retirees move closer to achieving a stable and organized financial future.
Sources:
https://www.dol.gov/sites/dolgov/files/ebsa/about-ebsa/our-activities/resource-center/publications/dol-top-10-ways-to-prepare-for-retirement-booklet-2023.pdf
https://www.aarp.org/money/retirement/steps-to-take-before-you-retire/
This material is designed to provide general information on the subjects covered and is intended purely for educational purposes. It should not be construed as individualized investment, legal, or tax planning guidance, nor does it serve as a comprehensive financial plan. No investment strategy, such as diversification or the use of target-date funds, can guarantee a profit or protect against loss in periods of declining markets. Diversification is an investment method used to help manage risk, but it does not eliminate market risk or ensure investment success. Target-date funds incorporate a changing asset allocation path (“glide path”) that gradually becomes more conservative over time; however, these funds are subject to market volatility, are not guaranteed, and may lose value—including at and after the target retirement date. Pursuant to IRS Circular 230, this information cannot be used to avoid tax penalties. Clients and prospective clients are strongly encouraged to consult with their own qualified legal, financial, and tax professionals regarding their unique circumstances prior to making any financial decisions. The source(s) used to prepare this material is/are believed to be true, accurate and reliable, but is/are not guaranteed. SWG5585748-0626
A Hidden Retirement Risk: The Cost of Avoiding Healthcare and Long-Term Care Planning

For many Americans approaching retirement, the focus is often on investment balances, Social Security timing, and creating reliable income streams. And those things are important! But there is a financial retirement risk that can often go underestimated or forgotten that deserves closer attention: healthcare and long-term care costs.
As unpleasant as the topic may be, avoiding this conversation doesn’t make the risk disappear. In fact, delaying healthcare and long-term care planning could increase financial strain later in life, potentially disrupting an otherwise well-constructed retirement plan.
Long-Term Care Is More Common Than Many People Think
Many pre-retirees assume long-term care is something that only affects a small percentage of older adults and assume they won’t be a part of that group. However, statistics suggest otherwise. According to the Urban Institute, the average 65-year-old has a nearly 70% chance of needing some type of long-term care during their lifetime. Furthermore, approximately 20% of adults will require that care for more than five years.
According to the U.S. Department of Health and Human Services, nearly 70% of today’s 65-year-olds will need some form of long-term care during retirement, and roughly 20% will require care for more than five years. Long-term care can include assistance with everyday activities such as bathing, dressing, mobility, meal preparation, or memory support.
Care may come in several forms, including:
- In-home care
- Adult day services
- Assisted living facilities
- Skilled nursing or nursing homes
- Informal caregiving from family members
While many people hope to age independently at home, the cost of even moderate assistance can be substantial, so it’s something worth paying attention to.
The Rising Cost of Care
Long-term care costs have climbed dramatically in recent years. According to AARP’s Public Policy Institute, median long-term care expenses increased sharply between 2019 and 2024, with home care and assisted living costs rising nearly 50%, adult day services rising 33%, and nursing home costs jumping 25%.
Current annual averages nationwide include:
- Around $26,000 annually for adult day services
- Approximately $60,000+ for moderate in-home care
- Nearly $128,000 annually for a private nursing home room
- Roughly $115,000 annually for a semi-private nursing home room
These figures stand in stark contrast to the typical American’s preparation. The median household income for adults 65 and older is roughly $60,000. This means even moderate home care (30 hours per week) can cost as much as an older adult’s entire annual income, while assisted living or nursing home care far exceeds it.
The Medicare Misconception
One of the most common retirement planning mistakes is assuming Medicare will cover long-term care expenses.
Medicare is a federal health insurance program that provides important healthcare coverage for those 65+ or with specific disabilities, including hospital care, physician visits, preventive care, and limited home health services. However, Medicare generally does not pay for ongoing custodial long-term care or assisted living expenses.
Many retirees are surprised to learn that Medicare only covers short-term skilled nursing rehabilitation under limited conditions, and only for up to 100 days following a qualifying hospital stay. Even then, daily copayments ($217 for 2026) apply after the first 20 days.
As a result, retirees often find themselves paying out of pocket much sooner than expected.
Medicaid and the Middle-Income Squeeze
If Medicare won’t pay, many assume Medicaid will. While Medicaid is the largest payer of long-term care services in the United States, qualifying is far from simple.
Eligibility rules are strict and vary by state. In many cases, individuals must “spend down” much of their assets before becoming eligible. This process can be complex, often requiring specialized legal guidance to navigate. Even then, choices around facilities and living arrangements may become limited, and you may be placed in a facility you would otherwise not choose or have to share a room with others.
Middle-income retirees may be affected the most by this as they earn too much for Medicaid but not enough to easily absorb six-figure annual care costs.
Why Early Planning Matters
The good news is that the earlier you plan, the more options you have. Starting earlier may lessen the savings burden through long-term growth and compounding.
Early planning also expands available options, including:
- Long-term care insurance
- Hybrid life insurance policies with long-term care benefits
- Annuities designed to supplement future care costs
- Health Savings Accounts (HSAs)
Long-term care insurance remains one of the more common planning tools. According to the American Association for Long-Term Care Insurance, a healthy 55-year-old man may pay around $1,750 annually for coverage, while women and couples often pay more due to longer life expectancies.
Importantly, premiums generally increase with age, making early evaluation beneficial.
Healthcare Planning Is Retirement Planning
Healthcare and long-term care costs are an important part of retirement planning and should be included in your holistic plan.
Retirement isn’t only about accumulating wealth. It’s also about protecting it from the risks that can quietly erode your financial confidence over time.
The sooner healthcare and long-term care planning become part of the retirement conversation, the more choices retirees are likely to have later in life.
Sources:
https://health.usnews.com/best-senior-living/articles/types-and-costs-long-term-care-facilities
https://www.nia.nih.gov/health/long-term-care/paying-long-term-care
https://www.aarp.org/caregiving/financial-legal/long-term-care-affordability-report/
https://crr.bc.edu/how-much-will-your-long-term-care-needs-cost-it-depends-on-how-average-you-are/
https://health.usnews.com/best-nursing-homes/articles/how-to-pay-for-nursing-home-costs
https://aspe.hhs.gov/reports/what-lifetime-risk-needing-receiving-long-term-services-supports-0
This material is provided as general information and is not intended to be specific financial or tax guidance. Long-term care insurance and life insurance riders contain fees, exclusions, policy charges, and terms for keeping them in force. Product guarantees are backed entirely by the financial strength and claims-paying ability of the issuing insurance company. Before making any decisions regarding your personal financial strategy, you should consult a qualified financial, legal, or tax professional to discuss your individual circumstances and objectives. The source(s) used to prepare this material is/are believed to be true, accurate and reliable, but is/are not guaranteed.
SWG 5506131-0526
A Hidden Retirement Risk: The Cost of Avoiding Healthcare and Long-Term Care Planning
For many Americans approaching retirement, the focus is often on investment balances, Social Security timing, and creating reliable income streams. And those things are important! But there is a financial retirement risk that can often go underestimated or forgotten that deserves closer attention: healthcare and long-term care costs.
As unpleasant as the topic may be, avoiding this conversation doesn’t make the risk disappear. In fact, delaying healthcare and long-term care planning could increase financial strain later in life, potentially disrupting an otherwise well-constructed retirement plan.
Long-Term Care Is More Common Than Many People Think
Many pre-retirees assume long-term care is something that only affects a small percentage of older adults and assume they won’t be a part of that group. However, statistics suggest otherwise. According to the Urban Institute, the average 65-year-old has a nearly 70% chance of needing some type of long-term care during their lifetime. Furthermore, approximately 20% of adults will require that care for more than five years.
According to the U.S. Department of Health and Human Services, nearly 70% of today’s 65-year-olds will need some form of long-term care during retirement, and roughly 20% will require care for more than five years. Long-term care can include assistance with everyday activities such as bathing, dressing, mobility, meal preparation, or memory support.
Care may come in several forms, including:
- In-home care
- Adult day services
- Assisted living facilities
- Skilled nursing or nursing homes
- Informal caregiving from family members
While many people hope to age independently at home, the cost of even moderate assistance can be substantial, so it’s something worth paying attention to.
The Rising Cost of Care
Long-term care costs have climbed dramatically in recent years. According to AARP’s Public Policy Institute, median long-term care expenses increased sharply between 2019 and 2024, with home care and assisted living costs rising nearly 50%, adult day services rising 33%, and nursing home costs jumping 25%.
Current annual averages nationwide include:
- Around $26,000 annually for adult day services
- Approximately $60,000+ for moderate in-home care
- Nearly $128,000 annually for a private nursing home room
- Roughly $115,000 annually for a semi-private nursing home room
These figures stand in stark contrast to the typical American’s preparation. The median household income for adults 65 and older is roughly $60,000. This means even moderate home care (30 hours per week) can cost as much as an older adult’s entire annual income, while assisted living or nursing home care far exceeds it.
The Medicare Misconception
One of the most common retirement planning mistakes is assuming Medicare will cover long-term care expenses.
Medicare is a federal health insurance program that provides important healthcare coverage for those 65+ or with specific disabilities, including hospital care, physician visits, preventive care, and limited home health services. However, Medicare generally does not pay for ongoing custodial long-term care or assisted living expenses.
Many retirees are surprised to learn that Medicare only covers short-term skilled nursing rehabilitation under limited conditions, and only for up to 100 days following a qualifying hospital stay. Even then, daily copayments ($217 for 2026) apply after the first 20 days.
As a result, retirees often find themselves paying out of pocket much sooner than expected.
Medicaid and the Middle-Income Squeeze
If Medicare won’t pay, many assume Medicaid will. While Medicaid is the largest payer of long-term care services in the United States, qualifying is far from simple.
Eligibility rules are strict and vary by state. In many cases, individuals must “spend down” much of their assets before becoming eligible. This process can be complex, often requiring specialized legal guidance to navigate. Even then, choices around facilities and living arrangements may become limited, and you may be placed in a facility you would otherwise not choose or have to share a room with others.
Middle-income retirees may be affected the most by this as they earn too much for Medicaid but not enough to easily absorb six-figure annual care costs.
Why Early Planning Matters
The good news is that the earlier you plan, the more options you have. Starting earlier may lessen the savings burden through long-term growth and compounding.
Early planning also expands available options, including:
- Long-term care insurance
- Hybrid life insurance policies with long-term care benefits
- Annuities designed to supplement future care costs
- Health Savings Accounts (HSAs)
Long-term care insurance remains one of the more common planning tools. According to the American Association for Long-Term Care Insurance, a healthy 55-year-old man may pay around $1,750 annually for coverage, while women and couples often pay more due to longer life expectancies.
Importantly, premiums generally increase with age, making early evaluation beneficial.
Healthcare Planning Is Retirement Planning
Healthcare and long-term care costs are an important part of retirement planning and should be included in your holistic plan.
Retirement isn’t only about accumulating wealth. It’s also about protecting it from the risks that can quietly erode your financial confidence over time.
The sooner healthcare and long-term care planning become part of the retirement conversation, the more choices retirees are likely to have later in life.
Sources:
https://health.usnews.com/best-senior-living/articles/types-and-costs-long-term-care-facilities
https://www.nia.nih.gov/health/long-term-care/paying-long-term-care
https://www.aarp.org/caregiving/financial-legal/long-term-care-affordability-report/
https://crr.bc.edu/how-much-will-your-long-term-care-needs-cost-it-depends-on-how-average-you-are/
https://health.usnews.com/best-nursing-homes/articles/how-to-pay-for-nursing-home-costs
https://aspe.hhs.gov/reports/what-lifetime-risk-needing-receiving-long-term-services-supports-0
This material is provided as general information and is not intended to be specific financial or tax guidance. Long-term care insurance and life insurance riders contain fees, exclusions, policy charges, and terms for keeping them in force. Product guarantees are backed entirely by the financial strength and claims-paying ability of the issuing insurance company. Before making any decisions regarding your personal financial strategy, you should consult a qualified financial, legal, or tax professional to discuss your individual circumstances and objectives. The source(s) used to prepare this material is/are believed to be true, accurate and reliable, but is/are not guaranteed.
SWG 5506131-0526
The Real Estate Puzzle: Navigating Liquidity, Equity, and Market Volatility in Retirement

For many Americans, the American Dream concludes with a paid-off home and a sense of financial independence. However, as retirees enter their golden years, a common financial paradox often emerges: being house-rich and cash-poor. While a primary residence might represent a significant portion of a retiree’s net worth, this asset is inherently illiquid, meaning you cannot easily translate its value to cover your costs of living
Managing real estate in retirement takes a shift in mindset from accumulation to optimization. It involves understanding the nuances of home equity, the impact of interest rates, and the strategic use of tools that can help provide liquidity.
The Seasonal and Economic Context
For retirees considering selling their home as a result of liquidity concerns, timing is often a primary consideration. The real estate market traditionally experiences peak home-buying season during the spring and early summer. According to historical trends, this is when buyer demand is highest, often leading to quicker sales and potentially higher closing prices. For a retiree looking to maximize their exit proceeds, listing during this window can be advantageous.
However, seasonal trends are currently colliding with a complex interest rate environment, and interest rates can be a dual-edged sword. High interest rates can dampen buyer enthusiasm, reduce the pool of eligible purchasers, and put downward pressure on home prices. For the retiree seller, this might mean a longer wait on the market or being more flexible on price. Conversely, if a retiree plans to downsize, high rates can make financing a new, smaller home more expensive, potentially offsetting some of the gains from the sale of the larger property.
Overall, the benefits and costs of selling may cancel out, leaving you with a difficult decision—perhaps a decision to stay in your home, despite liquidity considerations.
The Illiquidity Problem
The challenge for many retirees is the illiquidity of real estate. Unlike a brokerage account, where you can sell shares and receive cash within days, real estate can take months to liquidate. For retirees whose net worth is heavily concentrated in their home, this lack of spendable cash can limit their options during financial emergencies or market downturns.
One costly mistake a retiree can make is overestimating the accessibility of their home equity. Without a strategy to create liquidity, a retiree may make decisions that negatively impact their long-term financial goals simply to cover short-term living expenses.
Strategies for Flexibility and Cash Flow
To help avoid the illiquidity pitfall, retirees can manage their real estate with an eye toward flexibility.
Rather than viewing a property solely as a store of value, retirees can transform it into an income stream to help provide a stable floor for retirement. This might involve renting out a finished basement or converting a former primary residence into a long-term rental. But if your idea of a peaceful retirement doesn’t involve being a landlord, utilizing third-party property management may assist with maintaining flexibility.
And for those considering selling a property, remember that exit planning often begins years before the actual move. We can help guide you as you consult a tax professional to assess the tax implications and discuss ways the proceeds could be reinvested. Some retirees choose to take a portion of their home sale proceeds and place them into a fixed or immediate annuity. This effectively converts an illiquid physical asset into a guaranteed stream of cash that could last a lifetime, providing a level of stability that tends to fluctuate less than the real estate market.
Leveraging Equity with a HELOC
For retirees who do not wish to sell but need access to cash, a Home Equity Line of Credit (HELOC) can be a powerful tool. A HELOC allows a homeowner to borrow against the equity in their home on an as-needed basis, helping add flexibility and potentially serving as an emergency fund or a bridge during periods of financial transition.
But because HELOCs typically have variable interest rates, it’s important to remember that borrowing too much against your home’s equity could lead to high interest payments or foreclosure and deplete the home equity intended for emergencies, retirement, or downsizing.
Volatility Considerations: Navigating Market Dips
Real estate is sometimes viewed as an asset class that can complement stock market volatility, but it is not immune to its own fluctuations. A drop in the local housing market can reduce a retiree’s equity just as quickly as a dip on Wall Street can reduce a 401(k).
Acknowledging the impact of market dips is important for volatility protection. When the equity market experiences a downturn, retirees with diversified assets can potentially maintain flexibility by drawing from their real estate cash flow or a pre-established HELOC. This strategy aims to help retirees avoid liquidating depreciated assets to pay for basic needs.
Conversely, having a large piece of your assets in the real estate basket can be potentially problematic as well. If the housing market cools significantly, the ability to sell or borrow against a home might be more difficult. So, if downsizing is something you’re considering, remember that you could convert home sale proceeds into investments, financial tools designed to address your retirement risks more directly than having a large asset on your balance sheet that can cover your costs. Creating regular income from your assets, no matter what they are, can help lessen overall risk for a retiree from the adverse effects of liquidity and longevity risk.
Staying Ahead of the Curve
Real estate is often a cornerstone of retirement security, and active management can help keep it from becoming a frozen asset. By understanding the seasonal cycles of the market, the impact of interest rates, and the importance of liquidity, retirees can begin to understand how real estate might help them achieve their overall retirement goals.
No matter the strategy, the goal is to help your home work for you rather than you working for your home. A financial advisor can help you convert equity into regular income streams to potentially address your overall retirement needs. In an era of unpredictable market movement and economic shifts, a tailored plan that prioritizes flexibility, cash flow, and security can help you reach the financial independence you worked for, so let’s start the conversation.